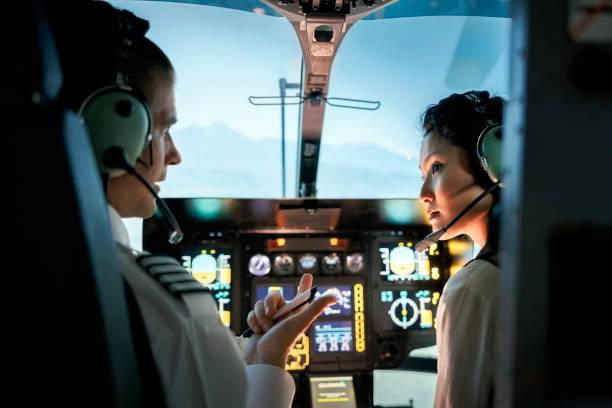
The global rotorcraft sector is advancing rapidly as modernization initiatives reshape both civil and military aviation. Operators are increasingly investing in advanced avionics to improve safety, navigation precision, and mission efficiency. Modern helicopters now rely heavily on integrated electronic systems that enhance communication, reduce pilot workload, and deliver real-time situational awareness across diverse operational environments.
Industry stakeholders are carefully evaluating the evolving dynamics of the Rotorcraft Avionics Market as demand rises for digital flight decks and connected aircraft platforms. Increasing adoption of glass cockpits, advanced autopilot technologies, and satellite-based navigation systems reflects a broader shift toward smarter rotorcraft ecosystems. These systems enable seamless coordination between onboard equipment and ground-based control centers.
A detailed Rotorcraft Avionics Market Analysis highlights the role of innovation in strengthening competitive positioning. Manufacturers are focusing on modular avionics architectures that allow flexible upgrades and simplified maintenance. This adaptability is particularly valuable for defense fleets that require mission-specific customization. In commercial aviation, operators seek systems that deliver reliability while minimizing downtime and lifecycle costs.
Safety remains a primary growth driver within the industry. Enhanced terrain awareness and warning systems, traffic collision avoidance systems, and weather radar technologies are being integrated into new and existing platforms. These solutions significantly reduce operational risks, particularly in challenging weather conditions or low-visibility environments. As regulatory authorities continue to tighten compliance standards, demand for certified avionics solutions is expected to rise steadily.
Technological convergence is another defining characteristic of the market landscape. The integration of artificial intelligence and machine learning capabilities is enabling predictive maintenance and advanced diagnostics. Real-time performance monitoring allows operators to identify potential component failures before they escalate, improving fleet readiness and reducing unexpected repair expenses. This predictive approach is transforming maintenance strategies across the rotorcraft ecosystem.
From a regional perspective, North America maintains leadership due to robust aerospace manufacturing capabilities and consistent defense spending. Europe demonstrates steady expansion supported by research initiatives and collaborative programs among aerospace firms. Meanwhile, Asia-Pacific is experiencing accelerated adoption driven by growing commercial aviation infrastructure and expanding emergency medical services operations.
Strategic partnerships are playing a crucial role in shaping the competitive environment. Avionics suppliers are collaborating with rotorcraft manufacturers to co-develop integrated solutions tailored to specific operational needs. These alliances streamline certification processes and ensure compatibility across multiple aircraft platforms. Additionally, investment in research and development continues to drive product differentiation.
Sustainability considerations are increasingly influencing procurement decisions. Lightweight avionics components contribute to improved fuel efficiency and lower emissions. Energy-efficient electronic systems also align with global environmental objectives while maintaining high performance standards.
The future of the industry is expected to be defined by greater connectivity, automation, and interoperability. Integrated mission systems, enhanced data analytics, and secure communication networks will continue to expand application possibilities. As technological sophistication grows, stakeholders who prioritize innovation, compliance, and operational efficiency are positioned to capitalize on emerging opportunities within the evolving rotorcraft avionics landscape.

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek